The economic situation turns from bad to worse
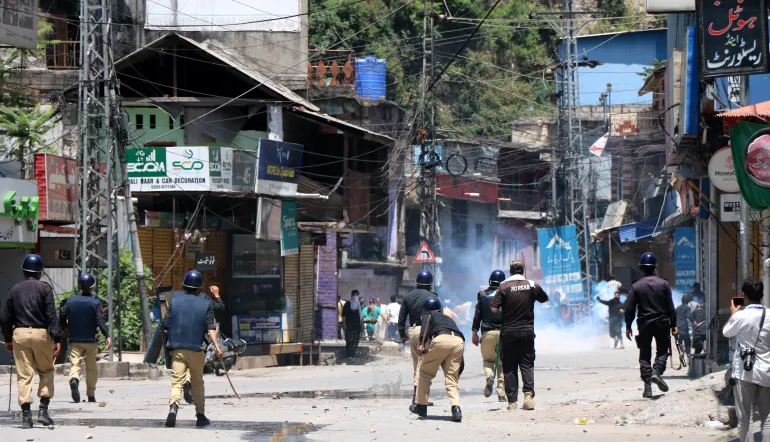
Pakistan-Occupied Kashmir is facing deepening economic stagnation, marked by slowing growth, rising unemployment, rising poverty, and shrinking development spending. High inflation eroded incomes, while weak industrialisation, declining infrastructure investment, and credit constraints constrained private-sector growth. Greater dependence on remittances and federal transfers reflects fragile fiscal capacity. Persistent governance gaps, climate stress, and weaknesses in human capital have reinforced a cycle of vulnerability, restricting sustainable and inclusive development.
A Worsening Development Trajectory of POK
Over the last decade, Pakistan-Occupied Kashmir, comprising parts of Jammu and Kashmir and Gilgit-Baltistan, has experienced persistent economic stagnation. This slowdown has become more evident since 2020, when the combined impact of the COVID-19 shock, inflation, fiscal stress, and governance constraints began to undermine growth momentum. Between 2020 and 2024/25, key indicators show declining productivity, rising unemployment, weakening public investment, and increasing dependence on external support. These trends have reshaped the region’s economic, infrastructural, and social landscape.
Growth Slowdown and Declining Economic Momentum
In 2020, the regional economy grew at an estimated rate of around 3.0 to 3.5 per cent, reflecting a moderate post-pandemic recovery and public-sector spending. By 2024/25, growth had decelerated sharply to nearly 1.5-2.0 per cent. This slowdown reflects weak private investment, reduced development spending, and macroeconomic instability in Pakistan.
Per capita income also stagnated in real terms. While average income stood at approximately USD 1,400 to 1,500 in 2020, it declined slightly to about USD 1,300 to 1,400 by 2024/25 due to high inflation and currency depreciation. This erosion of purchasing power has reduced household consumption and weakened local demand, further suppressing economic activity.
Fiscal Dependence and Shrinking Development Expenditure
A major contributor to economic deceleration is the region’s growing fiscal vulnerability. In 2020, public development spending accounted for 32 to 35 percent of regional budgets. By 2024/25, this share had fallen to 22 to 25 percent, as rising subsidy bills, debt servicing, and administrative costs crowded out capital expenditure.
At the same time, revenue self-generation declined from nearly 18 to 20 per cent of total expenditure in 2020 to only about 14 to 16 per cent in 2024/25. This has deepened dependence on federal transfers and emergency grants. As a result, development planning has become short-term and uncertain, limiting the implementation of large-scale infrastructure and productivity-enhancing projects.
Structural Weakness and Deindustrialisation
The narrow economic base of Pakistan-Occupied Kashmir has continued to constrain growth. In 2020, the industry contributed approximately 9 to 10 per cent of the regional GDP. By 2024/25, this share had declined further to nearly 7-8 per cent, indicating ongoing deindustrialisation.
Manufacturing remains limited to small-scale processing units, handicrafts, and informal workshops. The absence of industrial clusters, poor logistics, and weak access to finance have prevented industrial expansion. Consequently, the region has failed to generate high-productivity employment, reinforcing dependence on agriculture, government jobs, and remittances.
Comparative Economic Indicators: 2020 vs. 2024/25 (Approximate Trends)
| Indicator | 2020 | 2024/25 | Trend & Implication |
| Regional GDP Growth Rate | 3.0–3.5% | 1.5–2.0% | Slowing growth due to fiscal stress, inflation, and weak investment |
| Per Capita Income (USD) | 1,400–1,500 | 1,300–1,400 | Stagnation in real terms because of high inflation |
| Poverty Rate | 24–26% | 28–30% | Increase driven by price shocks and unemployment |
| Unemployment Rate | 6–7% | 9–11% | Rising youth and graduate unemployment |
| Public Development Spending (Share of Budget) | 32–35% | 22–25% | Decline due to rising debt and subsidy burden |
| Revenue Self-Generation | 18–20% | 14–16% | Growing dependence on federal transfers |
| Industrial Share in GDP | 9–10% | 7–8% | Continued deindustrialization |
| Agriculture Productivity Index | Base 100 | 92–95 | Decline due to climate stress and weak irrigation |
| Remittance Dependence (Share of Household Income) | 22–25% | 28–32% | Increasing reliance on external earnings |
| Inflation (Annual Average) | 8–9% | 22–25% | Severe erosion of purchasing power |
| Infrastructure Spending (Per Capita, USD) | 95–110 | 70–80 | Reduced investment and maintenance backlog |
| Bank Credit to Private Sector (Share of GDP) | 14–15% | 10–11% | Credit squeeze and low business expansion |
Employment Crisis and Rising Poverty
Economic slowdown has translated directly into labour-market stress. In 2020, unemployment was estimated at around 6 to 7 per cent. By 2024/25, it had increased to nearly 9-11 per cent, with youth and educated workers most affected.
Poverty levels have also risen. While about 24 to 26 per cent of the population lived below the poverty line in 2020, this share increased to nearly 28 to 30 per cent by 2024/25. High food prices, energy costs, and healthcare expenses have pushed many households into vulnerability.
The lack of stable employment has accelerated migration to urban centres and overseas markets. Remittances, which accounted for nearly 22 to 25 per cent of household income in 2020, rose to about 28 to 32 per cent by 2024/25. Although these inflows support consumption, they also reflect weak domestic job creation.
Agricultural Stress and Climate-Induced Productivity Losses
Agriculture remains a major source of livelihoods, yet its productivity has declined. Using 2020 as a base year with an index value of 100, agricultural productivity declined to nearly 92–95 by 2024/25. Climate variability, floods, landslides, soil erosion, and limited irrigation facilities have reduced crop yields.
Small landholdings, traditional farming practices, and limited access to modern inputs have further constrained output. Reduced agricultural incomes have weakened rural purchasing power and increased dependence on public assistance and remittances.
Infrastructure Gaps and Investment Decline
Infrastructure deficiencies remain a critical barrier to growth. In 2020, per capita infrastructure spending was estimated at around USD 95 to 110. By 2024/25, this figure declined to nearly USD 70 to 80, reflecting fiscal constraints and reduced development allocations.
Road connectivity remains uneven, particularly in remote mountainous districts. The power supply is unreliable despite the hydropower potential, and distribution losses remain high. Water supply and sanitation systems are outdated in many areas. Declining investment has also created a maintenance backlog, reducing the efficiency and lifespan of existing assets.
These deficiencies raise transportation and transaction costs, discourage industrial investment, and limit market integration, reinforcing economic stagnation.
Credit Constraints and Weak Private Sector Development
The private sector has been particularly affected by financial constraints. In 2020, bank credit to the private sector stood at around 14-15 per cent of regional GDP. By 2024/25, it had declined to nearly 10-11 per cent, reflecting tighter monetary policy, risk aversion, and limited collateral.
Small and medium enterprises face difficulties accessing formal finance, forcing them to rely on informal lenders at high interest rates. This restricts business expansion, technological upgrading, and employment generation. Low credit availability has thus become a structural impediment to regional development.
Education, Health, and Human Capital Limitations
The quality of education remains uneven. Limited digital infrastructure, shortages of trained teachers, and inadequate vocational institutions constrain skill development. As a result, many graduates remain unemployable in modern sectors, contributing to rising unemployment.
Healthcare facilities are concentrated in urban centres, while rural areas face shortages of doctors, medicines, and diagnostic services. High out-of-pocket medical expenses reduce household savings and increase poverty risk. These weaknesses in human capital formation lower labour productivity and weaken long-term growth prospects.
Governance Challenges and Institutional Fragility
Institutional weaknesses further reinforce economic deceleration. Limited fiscal autonomy, overlapping administrative authority, and political interference in project selection undermine policy consistency. Development priorities often change with political cycles, delaying project completion and discouraging private investment.
Weak monitoring mechanisms and gaps in transparency reduce the efficiency of public spending. As development resources shrink, governance shortcomings become more visible, deepening public dissatisfaction and economic uncertainty.
Social Inequality and Regional Disparities
Economic slowdown has widened disparities across districts and social groups. Areas with better road access and administrative presence attract more investment, while remote regions remain marginalised. Women’s participation in formal employment remains limited, restricting household incomes and economic inclusion.
Rising poverty, unemployment, and uneven service delivery have weakened social cohesion. These inequalities further limit the emergence of a broad-based growth process.
A Cycle of Stagnation and Vulnerability
In conclusion, between 2020 and 2024/25, Pakistan-Occupied Kashmir has witnessed a clear deterioration in economic performance. Growth declined from about 3.5 per cent to nearly 2 per cent, unemployment rose to double digits, poverty increased to around 30 per cent, development spending fell by nearly ten percentage points, and infrastructure investment declined sharply. At the same time, inflation surged, eroding incomes and savings, while dependence on remittances deepened.
These trends reflect a self-reinforcing cycle of fiscal dependence, weak diversification, infrastructure deficits, human capital constraints, and institutional fragility. Without a shift toward stable development financing, economic diversification, climate-resilient infrastructure, and stronger local governance, the region risks prolonged stagnation.
Views: 78